Accounting for Cryptoassets

As cryptoassets become increasingly common in commercial transactions and investment portfolios, companies must understand how to account for them appropriately under Singapore Financial Reporting Standards (International) [SFRS(I)]. Unlike traditional assets, cryptoassets do not fall neatly into existing categories such as cash, cash equivalents, or financial instruments, and therefore require careful classification based on their characteristics and intended use.

Classification of Cryptoassets

Cryptoassets generally fall into four broad categories:

  • Cryptocurrencies – Digital currencies used as a medium of exchange or store of value.

  • Utility Tokens – Tokens granting access to specific services, platforms, or products.

  • Asset Tokens – Tokens representing ownership or rights to underlying physical or financial assets.

  • Security Tokens – Tokens that mirror the economic rights of traditional securities such as equity or debt.

The accounting treatment depends on which category the asset falls into.

Accounting Treatment

Cryptocurrencies

  • If held for trading, they may be classified as inventory under SFRS(I) 2.

  • Otherwise, they typically meet the definition of intangible assets under SFRS(I) 1-38.

Utility Tokens

  • Depending on the holder’s purpose, they may be accounted for as inventory, intangible assets, prepayments, or financial instruments.

Asset Tokens

  • Accounting follows the standard relevant to the underlying asset the token represents.

Security Tokens

  • When they meet the definition of a financial asset, they fall under the scope of SFRS(I) 9 Financial Instruments.

Key Considerations for Businesses

Companies must evaluate cryptoassets based on their substance and economic reality, rather than solely their legal form. This assessment determines whether the asset represents a right to goods, services, cash flows, ownership interests, or simply an intangible digital resource. Because cryptoassets do not fit into one uniform accounting model, professional judgment and consistent application of relevant standards are essential.
InvoiceNow in Singapore: Simple Compliance When You Have the Right Support

Singapore is moving toward widespread adoption of InvoiceNow, the Peppol-based e-invoicing network that enables faster, more accurate and secure invoicing. While the upcoming requirements may seem daunting, the truth is: with the right support, InvoiceNow implementation can be quick, smooth, and hassle-free.

Our team specialises in helping businesses transition seamlessly, from system setup to GST compliance — so you can stay focused on running your business

Who Must Comply and When? (GST-Related InvoiceNow Requirements)

IRAS has defined specific compliance dates for voluntary GST registrants.

Companies that voluntarily register for GST within 6 months of incorporation

Compliance Date: From 1 November 2025
Newly incorporated companies registering early for GST must adopt InvoiceNow from this date.

All new voluntary GST registrants (regardless of incorporation date)

Compliance Date: From 1 April 2026
Any business voluntarily registering for GST on or after this date must begin issuing and receiving e-invoices through InvoiceNow.

These requirements mean that many new or growing businesses will need to adopt InvoiceNow as part of their GST onboarding process — and we can help ensure that transition is smooth and compliant.

Mandatory Requirement for Government Vendors – Effective 1 November 2025

From 1 November 2025, all new vendors onboarding with Singapore Government agencies must issue e-invoices exclusively through InvoiceNow.

This means:

  • You must be InvoiceNow-ready before contracting with government entities

  • PDF or paper invoices will no longer be accepted

  • Accurate e-invoice transmission becomes essential to avoid payment delays

With our support, we can ensure you meet the requirement well ahead of time.

How We Make InvoiceNow Adoption Easy for Your Business

Implementing InvoiceNow does not need to be complex. We specialise in helping companies of all sizes adopt it smoothly, with minimal disruption.

1. Guided System Setup and Activation

We handle the entire setup process:

  • Checking if your accounting software is InvoiceNow-ready

  • Activating your Peppol connection

  • Configuring your UEN and business profile

  • Ensuring invoices flow correctly into your accounting system

This means you avoid technical issues and enjoy a working solution from the start.

2. End-to-End Outsourced Accounting Support

Our accounting team ensures your operations run seamlessly after adoption:

  • Bookkeeping fully aligned with e-invoice workflows

  • AP/AR monitoring to ensure invoices are correctly sent and received

  • Troubleshooting any integration or data issues

  • Preparing monthly and quarterly reports incorporating InvoiceNow data

We take care of the accounting, so you don’t have to.

3. GST Review and Compliance Assurance

InvoiceNow still requires correct GST reporting — and we help ensure accuracy:

  • Checking GST codes and tax classification within your e-invoices

  • Verifying that your InvoiceNow data meets IRAS standards

  • Conducting periodic GST health checks

  • Supporting you during GST queries or audits

This reduces your compliance risk while maintaining smooth invoicing operations.

Let Us Make Your Digital Transition Seamless

The effective dates for InvoiceNow adoption are approaching — but with our support, implementation becomes easy, structured, and worry-free.

Whether you need help with InvoiceNow setup, outsourced accounting, or GST compliance, we’re here to guide you every step of the way.

Feel free to reach out. We’re ready to support your business through a smooth and successful transition

IFRS 18 – Key Technical Changes to Financial Statement Presentation

The International Accounting Standards Board (IASB) has issued IFRS 18 – Presentation and Disclosure in Financial Statements, which introduces a comprehensive restructuring of the statement of profit or loss and significantly expands disclosure requirements. Singapore is expected to adopt IFRS 18 into SFRS(I) for annual periods beginning on or after 1 January 2027, with full retrospective application.

Mandatory New Presentation Structure

Standardised Profit or Loss Categories

IFRS 18 introduces three mandatory, principle-based categories into the statement of profit or loss:

  • Operating

  • Investing

  • Financing

All income and expense items must be classified within these categories based on detailed application guidance. This represents a fundamental shift from existing practice, which allows more judgement in defining intermediate performance measures. The new structure aims to enhance cross-entity comparability and reduce diversity in practice.

Prescribed Subtotals

The standard introduces consistent subtotals across entities, such as:

  • Operating profit

  • Profit before financing and income taxes

Entities may no longer present bespoke subtotals unless they qualify as a Management-Defined Performance Measure (MPM) under the new disclosure framework.

Management-Defined Performance Measures (MPMs)

IFRS 18 establishes a specific framework for Management-Defined Performance Measures, defined as subtotals of income and expenses that:

  1. Are used in public communications outside the financial statements; and

  2. Reflect management’s view of an aspect of the entity’s overall financial performance.

Examples include Adjusted EBITDA, “core profit,” or other non-IFRS performance metrics commonly used in investor reporting.

For each MPM, entities must:

  • Provide a clear definition and description

  • Present a quantitative reconciliation to the nearest IFRS-defined subtotal

  • Disclose explanations of adjustments, including their nature and rationale

  • Present comparative information consistently across periods

This introduces discipline, transparency and comparability around non-GAAP performance metrics historically communicated without standardised requirements.

Enhanced Disaggregation Requirements

IFRS 18 tightens the requirements for disaggregation of income and expenses, requiring entities to:

  • Provide more granular breakdowns where necessary for users to understand performance

  • Avoid broad, aggregated line items such as “other expenses” unless immaterial

  • Apply a consistent basis for classification across the financial statements and notes

The standard specifies factors to assess whether items require further disaggregation, including nature, function, measurement basis, and variability.

Disclosures of “Unusual” Income and Expenses

IFRS 18 introduces explicit requirements to disclose unusual income and expense items, defined as items that:

  • Are not expected to recur in the near term; and

  • Have a significant effect on financial performance.

Entities must:

  • Identify such items based on the standard’s criteria

  • Disclose the amount, nature, and reason the item is considered unusual

  • Present comparative disclosures

This enhances users’ understanding of non-recurring items affecting performance trends.

Retrospective Application and Comparative Information

The standard requires full retrospective application, including:

  • Restating all comparative periods using the new P&L structure

  • Reclassifying historical income and expense items into operating, investing, and financing categories

  • Applying MPM definitions and reconciliations consistently to prior periods

  • Providing comparative disclosure of unusual items and disaggregation detail

As a result, entities presenting FY2027 financial statements will also present restated FY2026 comparatives under the IFRS 18 framework.

Implications for Reporting, Systems and Communications

The structural changes introduced by IFRS 18 will have significant implications for:

  • Financial statement presentation and mapping

  • Internal reporting frameworks

  • KPI and performance metric definitions

  • Investor and lender communication

  • Disclosure controls and accounting policy frameworks

Given the mandatory retrospective application and shift to standardised categories and subtotals, the adoption of IFRS 18 represents one of the most material presentation changes since the adoption of IFRS itself.

If you require technical guidance on IFRS 18 interpretation, presentation impacts, or disclosure implications, our team can support you with detailed analysis and implementation expertise.

How to Close or Restructure a Singapore Company

Companies in Singapore may be wound up, struck off, or restructured depending on their financial situation. Whether your company is dormant, solvent, insolvent, or under creditor pressure, it’s important to understand the appropriate exit or rescue options under Singapore law.

This guide outlines five main options to legally close, restructure, or resolve your company’s affairs:

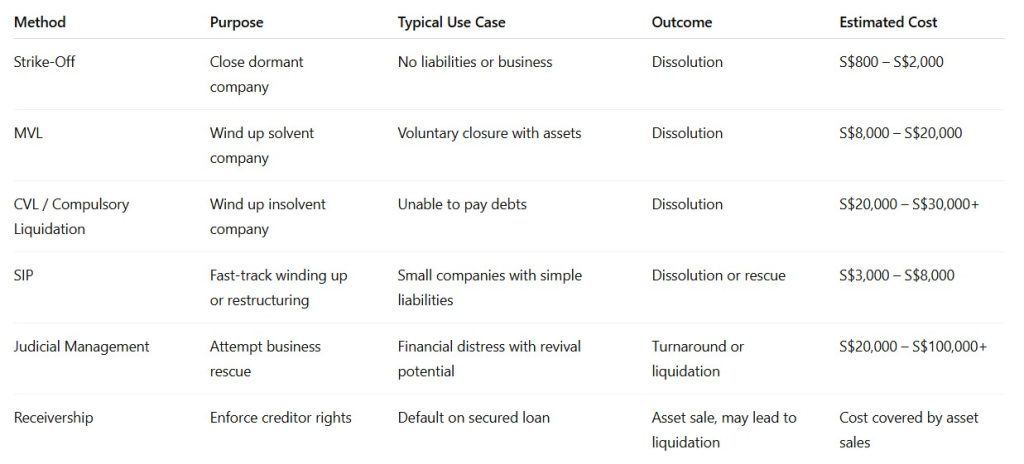
  • Strike-Off

  • Liquidation

  • Simplified Insolvency Programme (SIP)

  • Judicial Management (JM)

  • Receivership

Strike-Off (Deregistration)

Best for: Dormant companies with no assets or liabilities.

Strike-off is a voluntary process where a company applies to ACRA to be removed from the register.

Eligibility Conditions:

  • No business activity or assets.

  • No outstanding liabilities to IRAS, CPF, ACRA, or others.

  • No existing charges or ongoing legal proceedings.

  • Written consent of all directors.

Process:

  1. Finalise tax clearance with IRAS.

  2. Apply via BizFile+ to ACRA.

  3. ACRA issues a notice in the Gazette (30 days for objections).

  4. If no objections, company is struck off ~4 months from submission.

Cost Estimate:

  • ACRA fee: Free

  • Professional services: S$800 – S$2,000

Voluntary or Compulsory Liquidation

Best for: Companies with assets and liabilities.

There are 2 types:

  • Members’ Voluntary Liquidation (MVL) – company is solvent.

  • Creditors’ Voluntary Liquidation (CVL) – company is insolvent and initiated by directors.

  • Compulsory Liquidation – ordered by the Court upon creditor’s petition.

Steps (MVL):

  1. Declare solvency and pass resolution.

  2. Appoint licensed liquidator.

  3. Realise assets, pay creditors, distribute surplus to shareholders.

  4. Liquidator files final returns and company is dissolved.

Cost Estimate:

  • MVL: S$8,000 – S$20,000+

  • CVL/Compulsory: May exceed S$30,000 depending on complexity.

Simplified Insolvency Programme (SIP)

Best for: Small, insolvent companies with simple affairs.

Introduced during COVID-19, SIP is a fast-track version of liquidation or debt restructuring for qualifying companies.

Eligibility:

  • Company’s total liabilities must not exceed $2 million (including prospective and contingent liabilities)

Two streams:

  • Simplified Winding-Up Programme (SWUP) – lower-cost version of CVL.

  • Simplified Debt Restructuring Programme (SDRP) – similar to scheme of arrangement but streamlined.

Cost Estimate:

  • S$3,000 – S$8,000

Time taken:

  • 9 months

Judicial Management (JM)

Best for: Companies with potential to be saved or restructured.

JM is a court-supervised process where a judicial manager is appointed to take control and attempt to rehabilitate the company.

Who can apply:

  • The company

  • Its creditors

  • Its liquidator (if applicable)

Benefits:

  • Automatic moratorium (legal protection from creditors)

  • Breathing room to restructure debt or find a buyer

  • Judicial manager can terminate unprofitable contracts

Outcome:

  • Company may recover, be sold, or proceed to liquidation if turnaround fails.

Cost Estimate:

  • S$20,000 – S$100,000+ (depends on duration and complexity)

Receivership

Best for: Secured creditors enforcing security.

Receivership occurs when a creditor (usually a bank) appoints a receiver to seize and realise specific assets under a debenture.

Scope:

  • Receiver manages only secured assets (e.g., land, receivables).

  • Directors may retain control over the rest of the company.

Common Scenarios:

  • Default on a loan secured by company assets.

  • Receiver sells business as a going concern or liquidates assets.

Outcome:

  • Often leads to liquidation after enforcement is complete.

Cost Estimate:

  • Depends on value and nature of assets; borne by proceeds of realisation.

Summary of Closure & Insolvency Options

Conclusion

Singapore provides multiple legal avenues to close or restructure a company, tailored to its financial position and future prospects. Whether your company is dormant, struggling, or facing creditor pressure, understanding the available options—from strike-off to judicial management—can help you exit responsibly, protect stakeholders, and avoid future penalties.

Need help choosing the right path? Our team of company secretaries and insolvency professionals can assist with compliance, closure strategy, and stakeholder communication.

Updates: There is a revision to the SLP program.

Please refer to here for details.

Protecting Your Intellectual Property: Key Lessons from the Louis Vuitton Counterfeit Case

A recent Singapore High Court decision ordering an Instagram seller to pay S$200,000 to Louis Vuitton for infringing its trademarks highlights the serious consequences of IP violations—even by small-scale operators. This case offers important guidance for businesses on how to actively protect their IP assets in a digital, fast-moving marketplace.

Why IP Protection Matters

Infringement not only dilutes brand value but can also mislead consumers, damage reputation, and impact revenue. Ignoring unauthorised use or failing to enforce rights early may weaken legal protection over time.

Step-by-Step Guide: How Companies Can Protect Their IP

Step 1: Register Your IP Rights Early and Broadly

Ensure all key assets—logos, brand names, product designs, slogans, and trade secrets—are registered under the relevant IP categories (e.g. trademarks, designs, patents) in each jurisdiction you operate.

  • Louis Vuitton’s success in court was based on its existing trademark registrations.

  • Registration strengthens your legal position and simplifies enforcement.

Step 2: Monitor Online Platforms Regularly

Use internal teams or third-party services to monitor e-commerce sites, social media platforms, and independent online stores for counterfeit listings or unauthorised brand use.

  • In the Louis Vuitton case, the infringer used Instagram accounts to sell replicas with the company’s branding.

  • Detecting such activities early helps prevent scale-up and public confusion

Step 3: Take Swift Action Upon Discovery

Send cease-and-desist letters as a first response. If ignored or breached, escalate quickly to legal proceedings.

  • The seller in the Louis Vuitton case ignored initial warnings and continued operations under new account names, leading to court action.

  • Delay in response may be interpreted as tolerance or weaken your enforcement credibility.

Step 4: Secure Evidence Properly

Collect hard evidence of the infringement. This may include screenshots, transaction records, covert purchases, and expert assessments of the counterfeit nature of the goods.

  • Louis Vuitton purchased several counterfeit items to present clear, physical evidence in court.

  • Strong evidence supports both damages and injunctive relief.

Step 5: Pursue Legal Action Proportionately

If infringement persists, pursue legal enforcement based on the scale and impact of harm. Ensure damage claims are supported by data.

  • Louis Vuitton originally sought higher damages, but the court reduced it to S$200,000 after assessing actual harm and evidence.

  • Excessive or unsupported claims may be rejected by the courts.

Step 6: Monitor for Repeat Infringement

Even after a judgment or settlement, continue monitoring for the same infringer reappearing under different names or platforms.

  • The seller in the case rebranded after the initial warning and continued operations, which was considered in the court’s ruling.

  • Post-enforcement monitoring is essential to maintain control.

Step 7: Educate Internal Teams and Partners

Ensure marketing, sales, and procurement teams understand the company’s IP rights and know how to identify and escalate potential infringements.

  • Many infringement cases originate from distributors or third-party sellers misusing IP assets.

  • Training internal staff and partners reduces the risk of inadvertent violations.

Conclusion

The Louis Vuitton case is a clear example of the importance of defending intellectual property actively, even against small-scale or digital infringers. A structured, proactive approach—built on early registration, ongoing monitoring, and decisive legal action—can protect brand value and send a strong signal to the market that infringement will not be tolerated.

If your company has IP to protect, now is the time to ensure a system is in place—not just for registration, but for enforcement and long-term brand integrity

Regulatory Alert: Enhanced Compliance Requirements for RORC, ROND and RONS

Under the Companies and Limited Liability Partnerships (Miscellaneous Amendments) Act 2024 (CLLPMA), the Accounting and Corporate Regulatory Authority (ACRA) has updated the statutory disclosure regulations:

  • Announcement date: 9 June 2025
  • Effective date: 16 June 2025 (with a transition window for existing companies to file with the central registers, ending 31 December 2025)

This legislative framework significantly tightens reporting obligations for the Register of Registrable Controllers (RORC), Register of Nominee Directors (ROND) and Register of Nominee Shareholders (RONS). It removes historical grace periods, introduces central ACRA filing requirements, and substantially increases financial penalties for non-compliance.

Below is a summary of these statutory obligations, and why carrying out annual declaration exercises is a legal duty for all Singapore-incorporated companies and registered foreign companies.

1. Key Legislative Changes

To align Singapore with Financial Action Task Force (FATF) standards on Anti-Money Laundering (AML) and Countering the Financing of Terrorism (CFT), ACRA introduced the following changes:

  • RORC from day one: Entities incorporated on or after 16 June 2025 must set up, maintain and file their Register of Registrable Controllers on the date of incorporation via BizFile+, removing the former 30-day grace period.
  • Central lodgment of ROND and RONS: Companies and foreign companies must lodge nominee director and nominee shareholder particulars, including the identities of the underlying nominators, with ACRA’s central registers.
  • Annual controller verification: Entities must check with every registrable controller at least once a year, by sending each controller a notice in the form prescribed under the regulations, to confirm whether their recorded particulars are correct or have changed.

2. Statutory Timelines and Operational Requirements

Corporate officers and Registered Filing Agents (RFAs) must keep strictly to ACRA’s timelines:

  1. 7-calendar-day updating rule: Changes must be recorded in the registers within 7 calendar days after the controller confirms them, replacing the previous rule of 2 business days. If a controller does not reply within 30 days of the notice, the 7 days run from the end of that 30-day period.
  2. Audit-trail evidence: Registrable controllers must give signed and dated written confirmation that their particulars are accurate. Registers should not be updated based on verbal assurances.
  3. Foreign companies included: Registered foreign companies in Singapore must now keep a Register of Nominee Directors at their registered office or at the office of their corporate service provider.

3. Public Disclosure vs Data Privacy

ACRA balances regulatory oversight with commercial privacy safeguards:

  • Public business profile: A director’s or shareholder’s nominee status is shown on the company’s BizFile+ business profile.
  • Confidential central registers: The identity and particulars of the underlying nominator or ultimate beneficial owner (controller) lodged with ACRA’s central registers are not public. This information is available only to public agencies, for regulatory and law enforcement purposes.

4. Penalties for Non-Compliance

  • Fines of up to S$25,000 per offence: Failing to set up, maintain, update or lodge accurate RORC, ROND or RONS details is an offence punishable by a fine of up to S$25,000 per offence, up from the previous maximum of S$5,000.
  • False or misleading information: A new offence applies to giving false or misleading information, without due diligence, in response to a production order or inquiry from ACRA about the registers. This is also punishable by a fine of up to S$25,000.
  • Officer liability: Liability can extend to both the company and its officers, such as directors and company secretaries.

Official ACRA Guidance and Resources

For the detailed legislation and practice guidance, please refer to ACRA’s official publications:

Stay Compliant with Our Corporate Secretarial Team

Complying with ACRA’s requirements calls for active record management and systematic verification. Our Corporate Secretarial team helps corporate groups, foreign companies and local business owners manage annual confirmation cycles, prepare compliant declarations, and make timely BizFile+ lodgments, so that you stay audit-ready.

Accounting for Cryptocurrencies

As businesses in Singapore and globally explore new frontiers in digital finance, cryptocurrencies have increasingly appeared on corporate balance sheets. From technology firms like Tesla to financial institutions like DBS Bank, cryptoassets are no longer fringe investments. This shift raises an important question: How should cryptocurrencies and other digital tokens be accounted for under Singapore Financial Reporting Standards (International) [SFRS(I)]?

Cryptocurrency ≠ Cash or Financial Asset

Although often referred to as “digital money,” cryptocurrencies like Bitcoin or Ethereum do not meet the definition of cash or cash equivalents under SFRS(I) 1-7, as they are not legal tender and lack universal acceptance. Similarly, they are not financial assets under SFRS(I) 9, as they do not give holders contractual rights to receive cash or another financial asset.

Beyond Cryptocurrency: 4 Types of Cryptoassets

Cryptocurrency is just one category in the growing universe of digital tokens. The ISCA Financial Reporting Guidance (FRG) 2, titled “Accounting for Cryptoassets from a Holder’s Perspective”, classifies cryptoassets into four types, each with different accounting treatments:

Type of CryptoassetNature and Description
CryptocurrencyUsed as a medium of exchange or store of value; does not represent ownership rights or entitlements.
Utility TokenGrants access to specific services or products on a blockchain platform.
Asset TokenRepresents ownership of a physical or financial asset (e.g., real estate, commodities).
Security TokenRepresents equity or debt interests with associated contractual rights (e.g., dividends, repayment).

Accounting Treatment by Type

Type Applicable StandardsCommon Measurement Basis
Cryptocurrency- SFRS(I) 1-38 (Intangible Assets)- At cost less impairment
- SFRS(I) 2 (Inventories) - At cost less impairment or fair value less costs to sell (For broker-trader)
Utility Token- SFRS(I) 2 (Inventories)- At cost less impairment or fair value less costs to sell (For broker-trader)
- SFRS(I) 9 (Financial Instruments) - Fair value or amortised cost based on classification

- SFRS(I) 1-16 (Leases)- At cost less impairment
- SFRS(I) 1-38 (Intangible Assets)- At cost less impairment
- Prepayment- At amortised cost
Asset Token- Based on underlying assets
Security Token- SFRS(I) 9 (Financial Instruments) - Fair value or amortised cost based on classification

Conclusion

While cryptocurrencies are leading the headlines, companies should be aware that there are multiple types of cryptoassets, each with distinct accounting implications. The ISCA’s FRG 2 provides a structured framework to ensure that cryptoasset holdings are properly classified and presented under SFRS(I).

If your company holds or plans to invest in cryptoassets, it’s crucial to assess their nature and ensure compliance with the appropriate accounting standard. Our advisory team can help navigate this evolving space with clarity and accuracy.

Budget 2025: Key Measures for Businesses

Singapore’s Budget 2025 was delivered in Parliament on 18 February 2025 by Prime Minister and Finance Minister Lawrence Wong, in the year of Singapore’s 60th anniversary (SG60). This article summarises the measures most relevant to companies and business owners.

1. Corporate Income Tax Rebate for YA 2025

  • Companies receive a 50% corporate income tax rebate for YA 2025.
  • Companies that employed at least one local employee in 2024 receive a minimum cash payout of $2,000, paid automatically from the second quarter of 2025.
  • The total benefit is capped at $40,000 per company.

2. Tax Schemes Extended and Enhanced

  • Double Tax Deduction for Internationalisation (DTDi): the 200% tax deduction on qualifying market expansion costs is extended to 31 December 2030.
  • Mergers & Acquisitions (M&A) scheme: extended to 31 December 2030, with a 25% allowance on qualifying acquisitions of up to $40 million per YA and a 200% deduction on transaction costs, capped at $100,000 per YA.
  • Land Intensification Allowance: extended to 2030.
  • Innovation cost-sharing: a 100% tax deduction for payments made under approved innovation cost-sharing agreements.
  • Employee equity schemes: tax deduction for shares issued under employee equity-based remuneration schemes, from YA 2026.

3. Support for Enterprises

  • Enterprise Financing Scheme: the Trade Loan cap is raised permanently from $5 million to $10 million.
  • Market Readiness Assistance grant: the enhanced support cap of $100,000 per new market is extended to 31 March 2026.
  • SkillsFuture Enterprise Credit: a new $10,000 credit for eligible companies with at least three resident employees, to support workforce and enterprise transformation.
  • National Productivity Fund: topped up by $3 billion.
  • Enterprise Compute Initiative: up to $150 million to help companies adopt AI tools and computing resources.

4. Workforce and Wages

  • Progressive Wage Credit Scheme: government co-funding for wage increases given in 2025 raised from 30% to 40%, and for 2026 from 15% to 20%.
  • Senior Employment Credit: extended to the end of 2026 to support the hiring of workers aged 60 and above.
  • CPF monthly salary ceiling: rises to $8,000 from 1 January 2026, completing the increases announced earlier.

CPF contribution rates for senior workers from 1 January 2026:

Employee ageEmployerEmployeeTotal
Above 55 to 6016%18%34%
Above 60 to 6512.5%12.5%25%

5. Foreign Manpower Changes Announced Alongside the Budget

The Ministry of Manpower announced the following at its 2025 Committee of Supply debate:

  • S Pass: minimum qualifying salary raised to $3,300 ($3,800 for financial services) for new applications from 1 September 2025, and for renewals from 1 September 2026.
  • S Pass levy: a single levy of $650 a month applies across all tiers from 1 September 2025.
  • Work Permit: from 1 July 2025, the maximum period of employment is removed and the maximum employment age is raised to 63.

6. Support for Households

  • $800 in CDC vouchers per Singaporean household ($500 in May 2025 and $300 in January 2026).
  • SG60 vouchers of $600 for Singaporeans aged 21 and above, and $800 for those aged 60 and above.
  • A 60% personal income tax rebate for YA 2025, capped at $200.

What This Means for Your Business

Budget 2025 continued the cash relief of the corporate income tax rebate while extending key tax schemes to 2030, giving businesses more certainty for planning expansion and acquisitions. Employers should budget for higher CPF contributions for senior staff and the higher S Pass salary and levy requirements.

How We Can Help You

We can help you claim the tax rebate and deductions correctly, assess whether the DTDi and M&A schemes apply to your plans, and review your payroll and foreign manpower costs. Contact us to arrange a discussion.

新加坡公司指南

想在新加坡创业?我们帮您搞定!🚀

我们的团队精心准备了一份全面指南,帮助未来的企业主轻松完成公司注册流程。

无论您是本地企业家还是外国投资者,本指南都涵盖了您需要了解的一切——从商业结构和注册流程到税务合规和营业执照申请。

✅ 公司注册的逐步流程

✅ 关键要求和合规义务

✅ 实用见解,助您顺利创业

这份资源旨在为您节省时间,确保创业过程无忧无虑。立即下载指南,自信开启您的创业之旅!

新加坡创业指南

Guide to starting a company in Singapore

Starting a business in Singapore? We’ve got you covered! 🚀

Our team has prepared a comprehensive guide to help future business owners navigate the company incorporation process with ease.

Whether you’re a local entrepreneur or a foreign investor, this guide covers everything you need to know—from business structures and registration to tax compliance and licensing.

✅ Step-by-step incorporation process
✅ Key requirements and compliance obligations
✅ Practical insights for a smooth startup journey

This resource is designed to save you time and ensure a hassle-free experience as you embark on your business journey. Download the guide now and start your business with confidence!

Click to download the guide to doing business in Singapore.