Buying a Commercial Property in Singapore: Personal Name or Company?

For many business owners, buying their own office, shop or industrial unit is a major milestone. It ends the cycle of rent increases and, over time, builds an asset. But one question comes up early and is often decided too quickly: should you buy the property in your personal name, or through your company?

The answer affects your income tax, your GST position and how you finance the purchase, both now and many years down the road. Here is what we walk our clients through before they sign.

Option 1: Buying in Your Personal Name

Rental income and deemed expenses. If you rent the property out (including to your own company), the rental income is added to your personal income and taxed at personal rates of 0% to 24%. The good news is that you can claim deemed rental expenses of 15% of the gross rent, plus the actual mortgage interest, without having to keep receipts for those other expenses. It is simple and, for many owners, generous.

No GST to deal with, but no GST to claim. As an individual who is not GST-registered, you do not charge GST on the rent. However, if you buy from a GST-registered seller, such as a developer, the 9% GST on the purchase price is a cost you cannot recover.

Selling later. Singapore has no capital gains tax, so a gain on a genuine long-term investment is generally not taxed. There are no GST complications when you sell.

Option 2: Buying Through Your Company

Corporate tax rates and actual expenses. Rental income or business use is taxed at the corporate rate of 17%, reduced further by the partial tax exemption. The company can deduct its actual expenses, such as loan interest, property tax, maintenance and insurance.

GST can be claimed upfront. If your company is GST-registered and uses the property for its taxable business, it can generally claim back the 9% GST paid on the purchase. On a $1.5 million unit, that is $135,000 back in the company’s pocket, which is a real cash-flow advantage at the start.

The Catch: GST When You Deregister

This is the part many buyers overlook. A common scenario: years later, you wind down or sell the operating business, but keep the property. The company becomes an investment holding company earning passive rental income. Because that rent is usually well below the $1 million GST registration threshold, the company often deregisters from GST to avoid the ongoing GST filings.

At that point, the company must account for GST on the market value of the business assets it still holds, including the property. Because the GST is based on the property’s value at deregistration, not what you paid, a property that has gone up in value means a larger GST bill than the GST you originally claimed.

Example: your company buys a unit for $1.5 million and claims $135,000 of GST. Ten years later, the business has wound down and the company simply rents the unit out. It deregisters from GST when the unit is worth $2.2 million, and must now pay GST of about $198,000 (9% of $2.2 million), in cash, even though nothing has been sold.

Do Not Forget: Singapore Property Tends to Appreciate

Historically, Singapore property prices have tended to rise over the long term. That is good news for your net worth, but it also means the “GST holiday” you get by claiming GST upfront can turn into a bigger cash outflow later if the company ever deregisters. When you compare the two options, look at the whole life of the property, not just the day you buy it.

Financing Works Differently

  • Personal name: the loan is assessed against your personal income, and the Total Debt Servicing Ratio (TDSR) limit of 55% applies to property loans to individuals. A large commercial loan may reduce how much you can borrow for a home later.
  • Company: TDSR does not apply to a company. The bank looks at the company’s financial statements and cash flow instead. Banks commonly ask directors to give a personal guarantee, and younger companies may be offered a lower loan amount or less attractive terms.

Our advice: speak to your bank about both options before committing, and remember that a personal guarantee means the loan can still become your personal liability.

Questions to Ask Before You Decide

  • Will the property be used by your own business, or rented to third parties?
  • Is your company GST-registered, and is it likely to remain registered for as long as it owns the property?
  • How long do you plan to hold the property, and how might you eventually exit, through a sale or by passing it on?
  • What is your personal income tax bracket compared with the company’s effective tax rate?
  • How much can you borrow under each option, and are you comfortable giving a personal guarantee?

There is no one-size-fits-all answer. The right choice depends on your business, your cash flow and your long-term plans.

How We Can Help You

We help business owners compare the tax, GST and cash-flow impact of buying in their personal name or through a company, before they commit. Contact us to arrange a discussion before you sign the Option to Purchase.
10 Legal Ways to Reduce Tax in Singapore: A Practical Guide for Start-ups and Business Owners

The tax system rewards people who understand how it works. Singapore already has one of the most business-friendly tax regimes in the region, yet many start-ups and business owners still pay more tax than they need to, simply because nobody told them what they could claim.

Here are 10 legitimate ways to reduce your tax in Singapore, written with founders and growing businesses in mind.

1. Start-ups: Make Your First Three Years Count

If you have just incorporated, this is the single biggest tax advantage you will get, so plan around it.

For their first three Years of Assessment (YAs), qualifying new companies enjoy the Start-up Tax Exemption: 75% of the first $100,000 of chargeable income and 50% of the next $100,000 are tax-exempt. Most locally incorporated start-ups owned by individuals qualify, although investment holding and property development companies do not. After the first three years, the Partial Tax Exemption still applies to every company (75% of the first $10,000 and 50% of the next $190,000).

On top of that, companies receive a 50% Corporate Income Tax Rebate for YA 2026, capped at $40,000. If you employed at least one local employee in 2025, you also receive a minimum cash grant of $2,000 as part of this rebate.

What this looks like in practice: a new company with $100,000 of chargeable income pays tax on only $25,000. At 17%, that is $4,250, and the 50% rebate brings it down to about $2,125, an effective rate of roughly 2%.

Our advice: the early years are when your tax bill is lowest, so it is a good time to invest in the business, keep clean records from day one, and make sure your company is set up to qualify.

2. Do Not Be Afraid to Get Professional Help

Many entrepreneurs try to do everything themselves to save money. But professional fees are generally tax-deductible, including accounting, audit, tax filing, corporate secretarial services and legal fees on day-to-day business matters such as contracts and debt recovery.

That means the real cost of good advice is lower than it looks, and the benefits often outweigh it: avoiding late-filing penalties, claiming reliefs you did not know about, getting your structure right early, and freeing your time to grow the business.

The same goes for other day-to-day running costs such as rent, staff salaries and CPF, software subscriptions and marketing. Keep the invoices, as IRAS may ask for them.

3. Upgrade Yourself: Let the Company Pay for Your Courses

As a founder, the most valuable asset in your business is often you. Learning new skills, whether in digital marketing, finance, AI tools or your own industry, pays off for years, and the tax system supports it.

When the company pays for job-related training and courses for its staff, including working directors, the course and exam fees are tax-deductible for the company. For the employee, company-sponsored training is generally not taxable and does not attract CPF, as long as it forms part of the company’s training and is open to all staff to apply.

This matters even more now: the Course Fees Relief for individuals ended from YA 2026, so paying for a course out of your own pocket no longer gives you any personal tax relief.

Our advice: plan your learning budget through the company, keep the course invoices, and make sure the training is relevant to your work. Avoid bundling a holiday into an overseas course, as the holiday portion is taxable.

4. Travelling to Grow Your Business? Pay Yourself a Per Diem

This is one of the most commonly overlooked items for start-ups. When you or your team travel overseas to meet clients, attend trade fairs or explore new markets, the company can pay a per diem allowance to cover meals, local transport and incidental costs.

  • Per diem paid within IRAS’s acceptable rates for the country visited is not taxable to the employee, and that includes working directors.
  • For the company, it is a deductible business expense.
  • Only the portion above IRAS’s rates is taxable as income.

Our advice: set a simple travel policy, check IRAS’s published daily rate for each country before the trip, and record the travel dates and business purpose.

5. Working from Home? Claim Your Home Office Costs

Many start-ups begin life at the dining table. If you run your business from home as a sole proprietorship or partnership, you can claim the business share of your home expenses, such as electricity, internet and phone bills.

The claim should be worked out on a reasonable basis, for example the space you use for work and the hours you spend working, so keep a simple record of how you arrived at the figure. If your business is run through a company, talk to us about the right way to set this up.

6. Buying a Laptop for Work? Write It Off in Full

Small items you buy for the business, such as a laptop, phone, printer or office furniture, do not have to be depreciated slowly over many years.

  • Items costing $5,000 or less each can be written off in full in the year you buy them, up to a total of $30,000 per YA.
  • Computers and prescribed automation equipment can be written off 100% in one year regardless of cost.
  • Other equipment can generally be written off over three years.

Our advice: if you were planning to upgrade equipment anyway, buying before your financial year-end brings the tax saving forward.

7. Renovating Your Office? You Can Claim It, Including Designer Fees

Fitting out a new office or shop is a big cost for a growing business, and the good news is that much of it is tax-deductible.

  • Qualifying renovation and refurbishment costs can be claimed up to $300,000 for every three-year period (the current period is YA 2025 to YA 2027).
  • From YA 2025, designer and professional fees, such as interior designer and consultant fees, also qualify.
  • You can choose to claim the deduction over three years, or all in one year.

Note that structural works requiring approval from the building authorities do not qualify.

8. Expanding Overseas? Claim Double

Under the Double Tax Deduction for Internationalisation, qualifying market-expansion costs such as overseas business development trips, investment study trips and trade fairs can be deducted at 200%. Up to $150,000 of qualifying expenses per YA can be claimed without prior approval, rising to $400,000 from YA 2027, and the scheme runs until 31 December 2030.

Our advice: pair this with point 4. A well-documented overseas business trip can both reduce your company’s tax and provide tax-free per diem for your team.

9. Giving Back? Your Donation Is Worth 2.5 Times

Donations to Institutions of a Public Character (IPCs) qualify for a 250% tax deduction, now extended to donations made up to 31 December 2029. A $10,000 donation reduces your taxable income by $25,000, so giving to causes you care about also lowers your tax.

10. Plan How You Pay Yourself

As a founder, how you take money out of the company matters.

  • Salary or director’s fees are deductible for the company but taxed in your hands at personal rates of up to 24%.
  • One-tier dividends come from profits already taxed in the company, and are tax-free to you as a shareholder.

The right mix depends on your company’s profits and your other income, and it is worth reviewing each year. You can also reduce your personal tax by contributing to the Supplementary Retirement Scheme (up to $15,300 a year for Singapore Citizens and PRs, or $35,700 for foreigners) and by making CPF cash top-ups (relief of up to $8,000 for yourself and $8,000 for family members). Total personal reliefs are capped at $80,000 per YA.

Tax Planning, Not Tax Evasion

Everything above is about using the reliefs Singapore’s tax laws already provide. Arrangements set up mainly to avoid tax without genuine business substance can be challenged by IRAS, and under-declaring income or overclaiming expenses can lead to heavy penalties. Good tax planning starts with accurate records and good advice.

How We Can Help You

Whether you have just started your business or are ready to expand, our team can review your tax position, help you claim what you are entitled to, and set up your company and your own pay in the most tax-efficient way. Contact us to arrange a discussion.

Navigating IRAS Audits: Key Focus Areas & Penalties

The Inland Revenue Authority of Singapore (IRAS) has significantly stepped up its risk-based compliance audits. Finance teams and business leaders must ensure their accounting treatments align strictly with tax rules before filing.

Here is a quick look at the top three areas IRAS is scrutinising, and what happens if you are not compliant.

1. Transfer Pricing (TP) and Non-Compliance Penalties

IRAS actively audits related-party transactions to ensure compliance with the arm’s length principle.

  • Mandatory TPD: Businesses with gross revenue exceeding S$10 million (or that were required to prepare Transfer Pricing Documentation (TPD) in the prior year) must complete contemporaneous TPD before the tax filing due date.
  • Exemptions: Specified transactions falling below threshold limits (e.g. S$15 million for related-party loans, and S$2 million for service fees and royalties from YA 2026) may be exempt from detailed TPD.
  • Penalties and surcharges:
    • Failure to prepare, retain (for 5 years), or submit TPD within 30 days of request carries a fine of up to S$10,000 per offence under Section 34F.
    • IRAS also imposes a strict, non-deductible 5% surcharge on any upward transfer pricing adjustments made during an audit.

2. Unpaid Accruals

Under Singapore tax law, expenses are only deductible if they are genuinely incurred, with a definitive legal liability to pay.

IRAS is flagging long-outstanding balances, such as accrued director fees, management charges or bonuses, that sit on the balance sheet for multiple Years of Assessment without cash settlement. If an accrual is deemed contingent or lacks genuine payment intent, IRAS will disallow the tax deduction and reassess prior tax years.

3. Capital Accounts and Non-Income-Generating Assets

Balances in capital and intercompany accounts are under close review, particularly interest-free or low-interest loans extended to directors, shareholders or related companies.

  • Loans to directors: Interest savings on advances provided to directors in their employee capacity are treated as taxable benefits-in-kind (BIK) and must be reported in Form IR8A using IRAS benchmark interest rates.
  • Corporate interest adjustments: If a company incurs bank interest expenses while advancing interest-free funds to related entities or directors, IRAS requires an interest adjustment, disallowing a proportionate share (or all) of the company’s bank interest tax deductions.

Worried About Your Tax Risk? We Can Help

Navigating IRAS audit requirements requires a proactive review before the tax submission deadline.

If you are uncertain whether your company meets the transfer pricing threshold, have long-standing accruals on your books, or carry interest-free intercompany balances, reach out to our tax specialist team today. We can help review your positions, prepare compliant TPD, and safeguard your company against costly penalties.

GST Compliance Check: Have You Paid Your Suppliers Within 12 Months?

As a GST-registered business in Singapore, you are generally allowed to claim input tax based on valid tax invoices or import permits—even before settling the payment with your supplier.

However, under Inland Revenue Authority of Singapore (IRAS) regulations, you are required to pay your supplier within 12 months from the payment due date.

If any amount remains unpaid past this 12-month threshold, you must repay the previously claimed input tax back to the Comptroller of GST.

1. What happens if you make a partial payment within 12 months?

If you have settled a portion of the invoice but the remaining balance is still outstanding after 12 months, you must repay the input tax corresponding to the unpaid portion.

This repayment is calculated using the tax fraction (currently 9/109 at the 9% GST rate):

Repayment Amount = Unpaid GST-Inclusive Amount × 9/109

Example 1: Partial Settlement

  • Invoice total (GST-inclusive): $140

  • Partial payment made: $50

  • Unpaid balance after 12 months: $90

Calculation:

$90 × 9/109 = $7.43

Action Required: You must repay $7.43 of input tax back to the Comptroller of GST in your relevant GST return.

2. Can you reclaim the input tax if you pay your supplier later?

Yes. If you pay your supplier after the 12-month deadline, you are permitted to reclaim the repaid input tax, provided the payment is made within 5 years from the end of the accounting period in which the input tax was originally claimed.

Example 2: Delayed Full Settlement

  1. Original Claim: You claimed input tax in your GST return for the accounting period ending 30 June 2024.

  2. Repayment: Because the invoice was not paid within 12 months of the due date, you repaid the input tax to the Comptroller.

  3. Subsequent Payment: You paid the supplier in full on 1 June 2026.

Outcome: Since 1 June 2026 is within 5 years of 30 June 2024, you can safely reclaim the input tax in your GST return for the accounting period ending 30 June 2026.

Key Takeaways for Business Owners

  • Monitor Aging Payables: Regularly review your Accounts Payable aging report to flag invoices approaching the 12-month mark.

  • Maintain Accurate Records: Track when input tax was repaid to ensure you do not miss the 5-year window to reclaim it once settled.

  • Adjust GST Returns Promptly: Ensure input tax repayments or re-claims are correctly reported in the appropriate accounting periods to avoid non-compliance penalties.

Need Assistance with GST Compliance?

Navigating GST regulations and maintaining accurate tax records can be complex. Contact our team today to ensure your financial reporting remains compliant and optimized.

Missing Trader Fraud and GST Input Tax Claims: What Businesses Need to Know

The Inland Revenue Authority of Singapore (IRAS) has stepped up audits and investigations into Missing Trader Fraud (MTF), a form of GST fraud that can expose businesses to significant tax adjustments, penalties, and interest—even where the business believes it has acted in good faith.

This article outlines what Missing Trader Fraud is, why it matters, and the practical steps businesses must take to protect their GST input tax claims.

What Is Missing Trader Fraud?

Missing Trader Fraud typically arises when a supplier charges GST on sales but subsequently:

  • Fails to report the taxable supplies to IRAS; and

  • Does not account for or pay the output tax collected; and

  • Becomes uncontactable or ceases operations.

In such cases, IRAS may disallow the purchaser’s input tax claims if it concludes that the purchaser knew or should have known that the transaction was connected to fraudulent activity.

IRAS Audit Focus and the Knowledge Principle

IRAS applies the Knowledge Principle, under which input tax claims may be denied if a business:

  • Had actual knowledge of the fraud; or

  • Should reasonably have known, based on the circumstances, that the transaction was linked to Missing Trader Fraud.

Importantly, the absence of intent to defraud does not automatically protect a business. The key consideration is whether reasonable due diligence was performed.

IRAS has published guidance and conducts audits specifically targeting Missing Trader Fraud arrangements.

IRAS’ Three-Pillar Due Diligence Framework

To mitigate the risk of being implicated in Missing Trader Fraud, IRAS expects GST-registered businesses to implement due diligence measures based on the following three pillars:

Pillar 1: Identify and Assess Risk Indicators

Businesses should be alert to red flags such as:

  • Unusually low pricing or abnormal profit margins

  • Newly incorporated or dormant suppliers

  • Cash-only transactions or complex payment flows

  • Requests for rapid or backdated transactions

Pillar 2: Perform Due Diligence Checks

Reasonable checks should be performed and documented, including:

  • Verifying the supplier’s GST registration status

  • Understanding the supplier’s business activities and operating premises

  • Reviewing contractual terms and commercial rationale

  • Confirming bank account ownership and payment arrangements

Pillar 3: Respond to Identified Risks

Where risks are identified, businesses are expected to:

  • Seek clarifications or supporting documentation

  • Escalate concerns internally

  • Reconsider or decline the transaction if risks cannot be satisfactorily addressed

Merely identifying risks without taking appropriate follow-up action may not be sufficient.

Consequences of Non-Compliance

Where IRAS determines that due diligence was not performed to a reasonable standard, it may:

  • Deny GST input tax claims

  • Impose penalties and late payment interest

  • Initiate further audits or investigations

These outcomes can arise even if the underlying goods or services were genuinely received.

Practical Takeaways for Businesses

  • Due diligence is not optional—it is a key condition for protecting GST input tax claims.

  • Documentation is critical. Businesses should retain evidence of checks performed.

  • Higher-risk industries and transactions warrant enhanced scrutiny.

  • Internal GST controls and supplier onboarding procedures should be reviewed regularly.

Conclusion

Missing Trader Fraud remains a significant compliance risk in Singapore’s GST landscape. IRAS expects businesses to act with commercial awareness and to take proactive steps to assess and manage GST risks in their supply chains.

Implementing robust due diligence procedures aligned with IRAS’ guidance is essential to safeguarding GST input tax claims and avoiding costly disputes with the tax authority.

FAQ – GST change 2023

The amount relating to the option money paid before 1 Jan 2023 is subject to the GST rate of 7%.

The remaining payment will be subject to the GST rate of 8% as the property is only made available on/ after 1 Jan 2023.

If you receive full payment for the banquet before 1 Jan 2023, you should only charge 7% GST to your customer even if the banquet is to be held on/ after 1 Jan 2023.

If you only receive a deposit before 1 Jan 2023 and will receive the balance on/ after 1 Jan 2023, the deposit is subject to 7% GST while the remaining payment is subject to 8% GST.

You should also make clear to your customer that the portion of the banquet price paid before 1 Jan 2023 is inclusive of 7% GST while the balance to be paid on/ after 1 Jan 2023 is inclusive of 8% GST.

The letter of claim is not a bill for payment (i.e. invoice) for GST purposes.

On the understanding that you would only issue the invoice to the developer upon the certification of the work done in 2023 and collect payment from the developer thereafter, the time of supply would be on/ after 1 Jan 2023. Hence, the supply of your construction services would be subject to 8% GST.

However, you can choose to charge GST at 7% as you have completed the construction works before 1 Jan 2023.

As you would only issue the invoice and collect the retention sum from the developer in Nov 2023, the time of supply would be on/ after 1 Jan 2023. Hence, the retention sum would be subject to 8% GST.

However, you can choose to charge GST at 7% on the retention sum as you have completed the construction works before 1 Jan 2023.

You are not allowed to reflect GST at 8% before the rate change effective date of 1 Jan 2023.

The advance invoice pertaining to the services from 1 Oct 2022 to 31 Mar 2023 should reflect GST at 7%.

If you do not receive full payment before 1 Jan 2023, you are required to issue a credit note for the lower of remaining payment or the remaining value of service to be performed on/ after 1 Jan 2023. Thereafter, you are required to issue a new tax invoice in respect of the amount credited out to charge GST at 8%.

Alternatively, you may issue a credit note to cancel out the original invoice and at the same time, reissue new tax invoice(s) for the value of supply subject to GST at 7% and value of supply subject to GST at 8% .

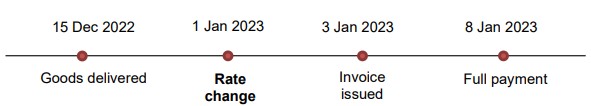
No. You are not allowed to issue a tax invoice with GST at 8% before the rate change effective date.

If you issue a tax invoice before 1 Jan 2023, you should reflect 7% GST on the tax invoice. If the payment is not received before 1 Jan 2023, you will need to issue credit note to cancel the original tax invoice and to issue a new tax invoice for the goods delivered after the rate change, showing 8% as the GST rate.

When you issue the tax invoice to your customer before 1 Jan 2023, you are advised to inform your customer on the potential GST adjustment under the rate change transitional rules to avoid dispute on the GST rate and GST amount payable on the supply.

You are not allowed to reflect GST at 8% before the rate change effective date of 1 Jan 2023. Hence, your invoice that is issued in Dec 2022 should reflect GST of 7% on the rental for the period 5 Dec 2022 to 4 Jan 2023.

Subsequently, assuming payment has not been received before 1 Jan 2023, you should issue a credit note by 15 Jan 2023 to cancel the portion of the rental for the period 1 Jan 2023 to 4 Jan 2023 billed at 7%, and to issue a new tax invoice at 8% for the same period.
The rental can be apportioned based on the number of days as follows:

Portion of rental that is subject to the GST of 7%
= Monthly rental x 27/ 31 days
Portion of rental that is subject to the GST of 8%
= Monthly rental x 4/ 31 days

When you issue the tax invoice to your customer before 1 Jan 2023, you are advised to inform your customers on the potential GST adjustment under the rate change transitional rules to avoid dispute on the GST rate and GST amount payable on the supply.

If you provide rebates to your customer that represent a discount for a past sale, you should calculate the GST on the rebate using the rate that is originally charged on the sale.

On the other hand, if the rebate is used to offset against the value of your next sale to your customer which takes place on or after 1 Jan 2023, you should charge GST at 8% on the net value of the sale.

For returned goods, you should adjust the GST using the rate that is originally charged on your supply of goods and maintain documentary evidence to show whether the goods returned were supplied before or on/after 1 Jan 2023.

Source: IRAS – FAQ

Changes to Singapore GST in 2023

In Budget 2022, the Minister for Finance announced that the GST rate will be increased from:

(i) 7% to 8% with effect from 1 Jan 2023; and

(ii) 8% to 9% with effect from 1 Jan 2024.

The revenue from the increase in GST will go towards supporting our healthcare expenditure, and to take care of our seniors

Rules for Supplies that span the change of GST rate

A supply spans the change of GST rate where one or two of the following events takes place wholly or partially on or after 1 Jan 2023: 

  • the issuance of invoice;
  • the receipt of payment (or the making of payment in respect of a reverse charge supply);
  • the delivery of goods or performance of services.

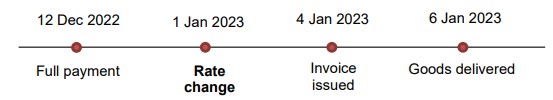
Invoice issued on or after 1 Jan 2023​

Full payment received before 1 Jan 2023 Goods delivered after 1 Jan 2023

If you issue an invoice for your supply on or after 1 Jan 2023 but you receive full payment before 1 Jan 2023, the supply is subject to 7% GST. 

Full payment received after 1 Jan 2023 Goods delivered before 1 Jan 2023

If you issue an invoice for your supply on or after 1 Jan 2023 but you have delivered all the goods or performed all the services before 1 Jan 2023, the entire value of the supply is subject to 7% GST. 

Invoice is issued before 1 Jan 2023

Full payment received or Goods delivered before 1 Jan 2023

If you have received full payment before 1 Jan 2023, or if you have delivered all the goods or performed all the services before 1 Jan 2023, the entire value of the supply is subject to 7% GST. 

Partial payment received or partial goods delivered before 1 Jan 2023​

If you do not receive full payment before 1 Jan 2023 and you have delivered or performed a part or all of the goods or services before 1 Jan 2023, you can elect to charge 7% GST on the higher of:

(a) The payment received is before 1 Jan 2023; or 

(b) The value of goods delivered or services performed is before 1 Jan 2023. 

The remaining value of the supply will be subjected to 8% GST.

Supply involving invoice issued before 1 Jan 2023 – full payment received after 1 Jan 2023​

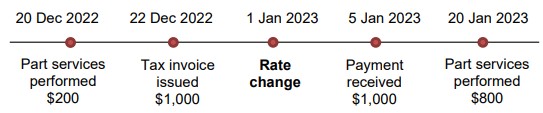
On 22 Dec 2022, you issue a tax invoice for your supply of services (value of $1,000) and you receive the full payment on 5 Jan 2023. You perform part of the services (value of $200) before 1 Jan 2023 and the remaining part of the services (value of $800) after 1 Jan 2023.

You must charge and account for GST at 7% ($70) for the tax invoice issued to your customer on 22 Dec 2022. As you do not receive any payment and only perform part of the services before 1 Jan 2023, under the transitional rules, you are required to issue the following to your customer by 15 Jan 2023, for that part of the services performed after 1 Jan 2023:

  • a credit note for $856 ($800 plus 7% GST of $56); and
  • a new tax invoice for $864 ($800 plus 8% GST of $64).

Supply involving invoice issued before 1 Jan 2023 – payments straddle 1 Jan 2023

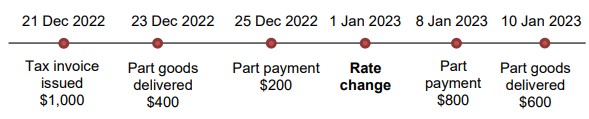
On 21 Dec 2022, you issue a tax invoice for your supply of services (value of $1,000). Before 1 Jan 2023, you delivered part of the goods (value of $400) and received a payment of $200. After 1 Jan 2023, you receive the remaining payment of $800 and perform delivered the other part of the goods (value of $600).

Under the transitional rules, you are required to issue the following by 15 Jan 2023, for that part of the goods delivered after 1 Jan 2023:

  • a credit note for $642 ($600 plus 7% GST of $42); and
  • a new tax invoice for $648 ($600 plus 8% GST of $48)

FAQs on Rental Relief and Property Tax Rebate for SMEs

Rental Relief

The rental relief framework, comprising the Rental Relief and the Additional Rental Relief, applies to eligible tenant-occupiers of prescribed properties in qualifying leases or licences that are in writing, or evidenced in writing, which are:

a) (i) Entered into before 25 March 2020; or (ii) entered into before 25 March 2020 but expired and renewed either automatically or in exercise of a right of renewal in the contract; and

b) In force at any time between 1 April and 31 July 2020 for qualifying commercial properties, and between 1 April and 31 May 2020 for other non-residential (e.g. industrial/office) properties.

Rental Relief

Tenant-occupiers must fall in the following category to be eligible for Rental Relief:

a) Small and Medium Enterprises (SMEs) with not more than S$100 million in annual revenue for the Financial Year 2018 or a later appropriate period where applicable, at the individual or entity level

  • If the tenant-occupier has not carried on business for 12 months or longer as at the last day of its financial year ending on a date in the year 2018, but has carried on business for 12 months or longer as at last day of its financial year ending on a date in the year 2019, the reference period will be FY2019 instead. Id the foregoing does not apply, but the tenant-occupier has carried on business for 12 months or longer as at the last day of its financial year ending on a date in the year 2020, where the date is on or before March 2020, the reference period will be FY 2020. For any other case, the tenant-occupier’s average monthly revenue from the time the tenant-occupier commenced business until 31 March 2020 (both dates inclusive) will be extrapolated for comparison against the $100 million annual revenue threshold.

Additional Rental Relief

The Additional Rental Relief will apply to tenant-occupiers who qualify for Rental Relief, have carried on business at the rented property before 25 March 2020 and meet the following additional criteria:

(a) The tenant-occupier is a company/entity incorporated in Singapore, and if it is a member of a Singapore group of entities during the period 1 Apr 2020 to 31 May 2020, the aggregate revenue for such a group is not more than S$100 million for the Financial Year 2018 or a later appropriate period where applicable; and

(b) The tenant-occupier suffered at least a 35% drop in average monthly gross income at the outlet level from 1 Apr to 31 May 2019, or alternative period if the tenant-occupier was not operational as of 1 Apr 2019.

Note: If the tenant-occupier commenced business after 1 Apr 2019, comparison will be against the period from the date of commencement of business to 24 Mar 2020 (both dates inclusive) to ascertain the decrease of 35% or more. 

a) Rental Relief for eligible SME tenants (supported by Government assistance):

Eligible tenant-occupiers in qualifying commercial properties and other non-residential properties will receive the rental relief through a waiver of rent from their landlords. Property owners will receive support through the: (a) Property Tax Rebate for Year 2020 announced in the Unity and Resilience Budgets; and (b) Government cash grant announced in the Fortitude Budget.

Eligible SMEs in qualifying commercial properties will receive up to 2 months’ waiver of their rent, and eligible SMEs in other non-residential properties (e.g. industrial and office properties) will receive up to 1 months’ waiver of their rent.

b) Additional Rental Relief for SME tenants (supported by landlords/ property owners):

Eligible SME tenant-occupiers who have seen a 35% or more drop in their average monthly gross income due to COVID-19 will receive up to an additional 2 months’ waiver of rent for qualifying commercial properties, and up to an additional 1 month’s waiver of rent for other non-residential properties (e.g. industrial and office properties).

For more details on the definitions of property in each category, please refer to this.

*The value of the rent to be waived is based on the contractual rent of the tenant, excluding any maintenance fee and charges for the provision of services such as cleaning and security.

  • In such a case, the tenant-occupier should provide its unaudited balance-sheet, profit and loss statement and cash flow statement for the period from the date of commencement of the business (at the prescribed property or any other place) to 31 March 2020 (both dates inclusive), supported by a statutory declaration by the tenant or (if the tenant is an entity) a relevant officer of the tenant.
  • If however, the above is also not available, the tenant should provide a statutory declaration by the tenant or (if the tenant is an entity) a relevant officer of the tenant stating that the revenue of the tenant, calculated using the formula 12xA is not more than $100 million, where A is the average monthly revenue from the business for the period from the date of commencement of the tenant’s business to 31 March 2020 (both dates inclusive).
  • A statutory declaration made in Singapore must be in the form set out in the First Schedule of the Oaths and Declarations Act (Cap. 211) and be made before a Commissioner for Oaths.

The Act provides for a moratorium on enforcement actions against eligible tenant-occupiers for non-payment of rent. Among other things, landlords are prohibited from taking the following actions on the tenant-occupier or the tenant-occupier’s guarantor/surety in relation to the non-payment of rent:

a) Terminating the lease or licence agreement;

b) Exercising the landlord’s right of re-entry or forfeiture under the lease or licence agreement; and

c) Starting or continuing court or insolvency proceedings.

This moratorium does not apply to tenants that are not tenant-occupiers, i.e. they are not operating on the property. It also does not apply to tenant-occupiers that do not meet the criteria for the rental relief, i.e. they are not a SME as defined. The moratorium also does not suspend interest due under lease agreements or license agreement. The moratorium ends when IRAS issues the notice of cash grant to the property owner, or on 31 December 2020 if no such notice is received before then.

If a landlord and tenant-occupier are unable to reach a compromise, the property owner and/or any intermediary landlord(s) may make an application using the prescribed form here within 10 working days after receiving (a copy of) the notice of cash grant, to have a rental relief assessor ascertain whether the tenant-occupier is eligible for Rental Relief and/or Additional Rental Relief. Please refer to the section Application for Assessment for details.

Under the Act, the rent that is payable by eligible tenants to their landlord for the relevant period of rental waiver is statutorily waived once qualifying property owners with eligible tenant-occupiers receive the notice of the cash grant issued by IRAS. This means that as an eligible tenant-occupier you do not need to pay rent for those months.


In the case where tenants have already paid rent for those months for which rent is waived, tenants can apply the rental waivers towards the next most immediate months of rent. If there is insufficient time left in the lease, tenants can obtain a refund from the landlord.


In cases where landlords had earlier provided assistance to their tenants or reached an agreement to provide assistance to their tenants, in the form of monetary payments or reduction of payments due under the lease agreement, or landlords have passed on the benefit of any Property Tax Rebate for Year 2020 in respect of the property, these can be offset from the landlords’ rental waiver obligations.

The Property Tax Rebate for Year 2020 for non-residential properties and the Government cash grant are based on the Annual Value of the property. This may not be equivalent to the rental waiver to be provided by landlords, which is based on the contractual rent. Tenants will still have to pay for maintenance fee and charges for the provision of services such as cleaning and security. Nevertheless, the landlord is obliged to provide the rental waiver based on the contractual rental as defined, not based on grant by the Government. The Property Tax Rebate and Government cash grant are not intended to cover the full amount of rental waivers exactly.

The Government recognises that there are landlords who may face genuine financial hardship.Landlords who meet all the following criteria may apply to a rental relief assessor to reduce the amount of Additional Rental Relief they have to provide:

a) The applicant landlord must be an individual or a sole proprietor and is the owner of the prescribed property;

b) The aggregate of the annual value of all investment properties (including the prescribed property) owned (whether solely or jointly with another person and whether directly or through one or more investment holding companies) is not more than S$60,000 as at 13 April 2020; and

c) The rental income derived from the property in question in Year of Assessment 2019 constituted 75% or more of the landlord’s gross income.

If the landlord meets the grounds of financial hardship above, the rental relief assessor may halve the amount of Additional Rental Relief to be borne by the landlord, i.e. one month’s rental waiver for qualifying commercial properties, or half a month’s rental waiver for other non-residential properties (e.g. industrial and office properties). The remaining rent payable will be borne by the tenant.

Property Tax Rebate

*Property Tax Rebate is different from Rental Relief

Property TypeComponentTax Rebate
HotelHotel Rooms100%
Function Rooms100%
Shops, restaurants, gym, tenements such as space for vending machine, base station and tour desk100%
Offices that are not used in connection with the operation of the hotel such as serviced offices30%
Retail MallShops and restaurants100%
Offices30%
Office BuildingOffices30%
Shops and restaurants100%
In-house gym that are used exclusively by the occupants of the office building
30%

Owners of qualifying properties are required to unconditionally and fully pass on to their tenant(s) the rebate for the property tax account that is attributable to the rented property based on the period it was rented out, by either reducing or offsetting current or future rentals or  through a payment to their tenant(s), within the prescribed timeframe.

Failure to properly pass on the rebate, or to keep the records (e.g. information on the amount, manner and time of pass on) until 31 Dec 2023, without reasonable excuse, is an offence. Those guilty of such an offence shall be liable on conviction to a fine not exceeding $5,000.

The property owners are to continue to pass on the rebate to their tenants despite any outstanding objections lodged for the year 2020. 

China’s Income Tax Policy in Relation to Overseas Income

On 17 January 2020, China’s Ministry of Finance and State Taxation Administration jointly issued the “Announcement on Individual Income Tax Policy in relation to Overseas Income” (Ministry of Finance and State Taxation Administration Announcement 3 of 2020). This announcement applies from the 2019 tax year. This means that income earned overseas by China tax residents will be taxed. 

Announcement 3 sets out the relevant policies regarding this new income tax policy. The key contents include:

  • Classification of overseas income
  • Calculation of taxable income
  • Foreign tax credit (“FTC”)

Residence rules

An individual is domiciled in China if:

(a) They habitually reside in China by reason of permanent registered address, family ties, or economic interests; or

(b) holds a Chinese passport or a hukou (household registration).

Classification of Overseas Income

The following categories of income are considered as overseas income:

Income categoriesBasis of income sourcing
(1) Income from provision of labour services outside China (including employment income and independent personal service income)The overseas location where the labour or employment activities are carried out.
(2) Authors’ remuneration paid and borne by enterprises and other organisations outside China;The overseas location of the enterprise or organisation which pays and bears the remuneration.
(3) Royalties received from the grant of concessions outside China;The overseas location where the concessions are utilised.
(4) Income from business operations and productions outside China;The overseas location where business operation or production is carried out.
(5) Interest and dividend income obtained from enterprises, other organisations and non-resident individuals outside China;The overseas location where the interest and/or dividend paying parties are based.
(6) Income from lease of overseas properties;The overseas location where the leased property is used.
(7) Capital gains from the transfer of real estate, transfer of equity stocks, stock options, or other financial assets (hereinafter referred to as financial assets) of overseas enterprises or other organisations, or from the transfer of other assets outside China;Real estate: the overseas location where the asset is located;
Financial assets: the overseas location where the invested enterprise or other organisation is based.
It is worth noting that if more than 50% of the fair value of the assets of the invested enterprise or other organisation comes directly or indirectly from real estate located in China at any time during the three years (36 consecutive months) prior to the transfer, the gains from the transfer of the assets would be deemed as China sourced.
(8) Incidental income obtained from enterprises, other organisations and non-resident individuals outside China;The overseas location where the incidental income paying parties are based.
(9) Separate rules may apply if otherwise determined by the Ministry of Finance or the State Taxation Administration.N/A

Personal Income Tax Rate

The following table shows the latest Income Tax Rate for residents in China.

Annual taxable income (CNY) Tax rate (%)Quick deduction (CNY)
0 to 36,00030
Over 36,000 to 144,000102,520
Over 144,000 to 300,0002016,920
Over 300,000 to 420,0002531,920
Over 420,000 to 660,0003052,920
Over 660,000 to 960,0003585,920
Over 960,00045181,920

How to calculate Taxable Income?

Domestic and foreign income subject to consolidated tax calculation

Comprehensive income

Annual comprehensive income = comprehensive income within China + comprehensive income from overseas

Income from business operations

Annual operating income = income from domestic operations + income from overseas operations

Losses from business operations in a particular overseas jurisdiction cannot be offset against income from operations in China or other overseas locations. However, the losses may be used to offset business operating income at the same location in future tax years, based on the relevant tax law in China.

Domestic and foreign income subject to separate tax calculation

Income derived from interest, dividends, property lease, property transfer, and incidental income cannot be consolidated with China-sourced income and shall be subject to tax calculation separately.

Foreign Tax credit ("FTC")

Announcement 3 makes it clear that where resident taxpayers receive overseas income during a tax year, FTC will be granted where foreign income tax has been paid in the overseas location in accordance with the tax law in that jurisdiction, subject to limits. The formula is as follows:

Tax / refund due for the tax year = total tax liability for the tax year – overseas tax liability allowable as credit (not exceeding the tax credit limit)

The amount of overseas tax exceeding the tax credit limit can be utilised in the following five tax years.

Overseas income not allowed for FTC

The following are the circumstances that are not allowed and shall be excluded from the FTC claim:

  1. Overseas tax paid or collected by mistake;
  2. Tax which should not be levied in the overseas jurisdiction under the Double Tax Treaty between China and the foreign country (or under the Double Tax Arrangement between Mainland China and Hong Kong and Macao);
  3. Late payment interest and/or penalties imposed by overseas tax authorities for underpayment or late payment of overseas income tax;
  4. Overseas income tax which is due for refund or compensation from the overseas tax authorities;
  5. Overseas income which is tax-exempt under the China IIT Law and Implementation Rules.

Singapore’s Tax Treaty with China

As there is an agreement between The Government of The Republic of Singapore and The Government of The People’s Republic of China, China residents receiving an income from Singapore or vice-versa, will be eligible for double tax relief if conditions are met. However, this is not an exemption of tax, but rather a reduction of tax.
According to Article 22 of the treaty, elimination of double taxation in China shall be eliminated as follows:

(a) Where a resident of China derives income from Singapore the amount of tax on that income payable in Singapore in accordance with the provisions of this Agreement, may be credited against the Chinese tax imposed on that resident. The amount of the credit, however, shall not exceed the amount of the Chinese tax on that income computed in accordance with the taxation laws and regulations of China.

(b) Where the income derived from Singapore is a dividend paid by a company which is a resident of Singapore to a company which is a resident of China and which owns not less than 10 per cent of the shares of the company paying the dividend, the credit shall take into account the tax paid to Singapore by the company paying the dividend in respect of its income.

In Singapore, double taxation shall be avoided as follows:

(a) Where a resident of Singapore derives income from China which, in accordance with the provisions of this Agreement, may be taxed in China, Singapore shall, subject to its laws regarding the allowance as a credit against Singapore tax of tax payable in any country other than Singapore, allow the Chinese tax paid, whether directly or by deduction, as a credit against the Singapore tax payable on the income of that resident.

(b) Where such income is a dividend paid by a company which is a resident of China to a resident of Singapore which is a company owning directly or indirectly not less than 10 per cent of the share capital of the first-mentioned company, the credit shall take into account the Chinese tax paid by that company on the portion of its profits out of which the dividend is paid.

Note:

Singapore employment income is not taxed in China according to the provisions of Articles 16, 18 and 19 of the treaty, salaries, wages and other similar remuneration derived by a resident of a Singapore State in respect of an employment shall be taxable only in Singapore unless the employment is exercised in the China. If the employment is so exercised, such remuneration as is derived therefrom may be taxed in China.

When it comes to profits earned from interest, royalties and dividend payments, special reduced rates apply, as follows:

Dividends

Dividends paid by a company which is a resident of China to a resident of Singapore may be taxed in Singapore.

However, such dividends may also be taxed in China of which the company paying the dividends is a resident and according to the laws of that State, but if the beneficial owner of the dividends is a resident of Singapore, the tax so charged shall not exceed:

(a) 5 per cent of the gross amount of the dividends if the beneficial owner is a company (other than a partnership) which holds directly at least 25 per cent of the capital in the enterprise paying the dividends;

(b) in all other cases, dividend payments are taxed at a rate of 10%.

Interest

Income arising from interest issued by a bank or financial institution which is a resident of China to a resident of Singapore, may be taxed in Singapore.

However, such interest may also be taxed in China of which the bank or financial institution paying the interest is a resident and according to the laws of that State, but if the beneficial owner of the interest is a resident of Singapore, the tax so charged shall not exceed:

(a) 7 per cent of the gross amount of the interest if it is received by any bank or financial institution

(b) 10 per cent of the gross amount of the interest in all other cases.

Royalties

Royalties in this treaty means payments of any kind received as consideration for the use of, or the right to use, any copyright of literacy, artistic or scientific work including cinematograph films, or films or tapes for radio or television broadcasting, any computer software, patent, trade mark, design or model, plan, secret formula or process, or for the use of, or the right to use, industrial, commercial or scientific equipment or for information concerning industrial, commercial or scientific experience.

These royalties derived from China and paid to a resident of Singapore, may be taxed in Singapore, and vice-versa.

However, if the beneficial owner of the royalties is a resident of Singapore, the tax charged shall not exceed 10 per cent of the gross amount of the royalties.  

IRAS – Extended Filing Deadline [Updated]

Due to the extended Circuit Breaker to 1 June 2020, IRAS is providing an automatic extension of deadlines for tax filing for individuals and businesses.

Tax TypeOriginal Filing DeadlineExtended Filing Deadline
[New]
Income Tax for Individuals (including sole
proprietors and partnerships)
18 Apr 202031 May 2020
Income Tax for Trusts, Clubs and
Associations
15 Apr 202030 Jun 2020
[Updated]
Estimated Chargeable Income (ECI) for
companies with Financial Year ending
Jan 2020
30 Apr 202030 Jun 2020
[Updated]
Estimated Chargeable Income (ECI) for
companies with Financial Year ending
Feb 2020
31 May 202030 Jun 2020
[Updated]
GST Returns for accounting period ending
Mar 2020
30 Apr 202011 May 2020
S45 Withholding Tax Forms due in Apr 202015 Apr 202015 May 2020
Tax Clearances for foreign employee in
Apr 2020
–30 Jun 2020
[Updated]
Tax Clearance for foreign employees
due in May 2020
–30 Jun 2020
[Updated]